Austin, Texas

Mortgage insights for Austin & Texas buyers

Rates, programs and strategy from Wise Capital Mortgage's Austin loan officers — updated for today's market.

Looking for a quick answer instead?Browse 330+ questions on DSCR, hard money, FHA/VA/USDA, bank statement loans and more — searchable in one place.
Tiered chart showing DSCR loan credit score bands from 620 through 760 with corresponding leverage and pricing outcomes
DSCR
DSCR Loan Credit Score: Tiers, Traps, and How to Move Up One
The credit tiers DSCR lenders price from, which score they actually pull, what derogatories cost you, and how to move up a tier before you lock.
Worked debt service coverage ratio calculation showing gross monthly rent divided by principal, interest, taxes, insurance and HOA
DSCR
How to Calculate DSCR (And What Lenders Do Differently)
Work the DSCR formula step by step, see the four places lenders calculate it differently than you do, and stress-test the ratio before you apply.
Timeline showing a hard money loan term overlapping with a DSCR refinance process from rehab completion through payoff
Bridge
Hard Money to DSCR: The Refinance Handoff, Step by Step
The transaction mechanics of exiting a hard money loan into a DSCR refinance: overlapping clocks, appraisal timing, lease requirements and payoff.
Chart comparing debt service coverage ratios across Central Texas counties at matched purchase prices and rents
Local
Austin DSCR Loans: What the Tax Rate Does to Your Ratio
Central Texas property taxes sit in the DSCR denominator and cost Austin investors two pricing tiers. How to model it, and which submarkets still clear.
Framework diagram showing the four state-level variables that change debt service coverage ratio outcomes across markets
DSCR
DSCR Loans by State: What Actually Changes Across State Lines
Property tax, insurance, foreclosure process and prepay enforceability all change by state, and all change your DSCR. A framework for any market.
Stage by stage flip project timeline showing acquisition, draw schedule, listing and payoff with carrying costs at each phase
Fix & Flip
Fix and Flip Loans: The Deal Lifecycle From Offer to Payoff
What happens at each stage of a flip loan, where projects actually go wrong, and the carry cost per day that decides whether the margin survives.
Cost comparison chart showing hard money and conventional financing expenses over a six month holding period
Compare
Hard Money vs Conventional: What Speed Is Worth in Dollars
Hard money costs multiples of conventional. The break-even math for when speed and condition flexibility are worth paying for, and when they are not.
Three overlapping leverage caps for a fix and flip loan showing loan to cost, after repair value and as-is value with the lowest result binding
Fix & Flip
LTV, LTC and ARV: Three Caps, and Which One Binds Your Deal
Flip lenders apply three leverage caps and fund the lowest result. How to calculate all three, find the binding one, and change it before you bid.
Complete flip cost model showing acquisition, financing, holding and selling costs subtracted from after repair value
Tools
Fix and Flip Calculator: Every Cost Line Investors Forget
The 70% rule is a screen, not a model. The complete cost stack for a flip, the six lines investors leave out, and how to build a real projection.
Underwriting checklist for a hard money loan file showing property, borrower, scope and exit documentation categories
Hard Money
Hard Money Loan Requirements: The Underwriting File, Item by Item
What hard money lenders verify, the liquidity test most investors fail, and the complete document list that gets a file to closing without conditions.
Leverage comparison showing cash required for a first-time investor versus an experienced investor on the same fix and flip project
Hard Money
Hard Money for First-Time Investors: What the Experience Gap Costs
First-time flippers get less leverage and pay more. What the gap costs in dollars, how to close it faster, and the mistakes that end first projects.
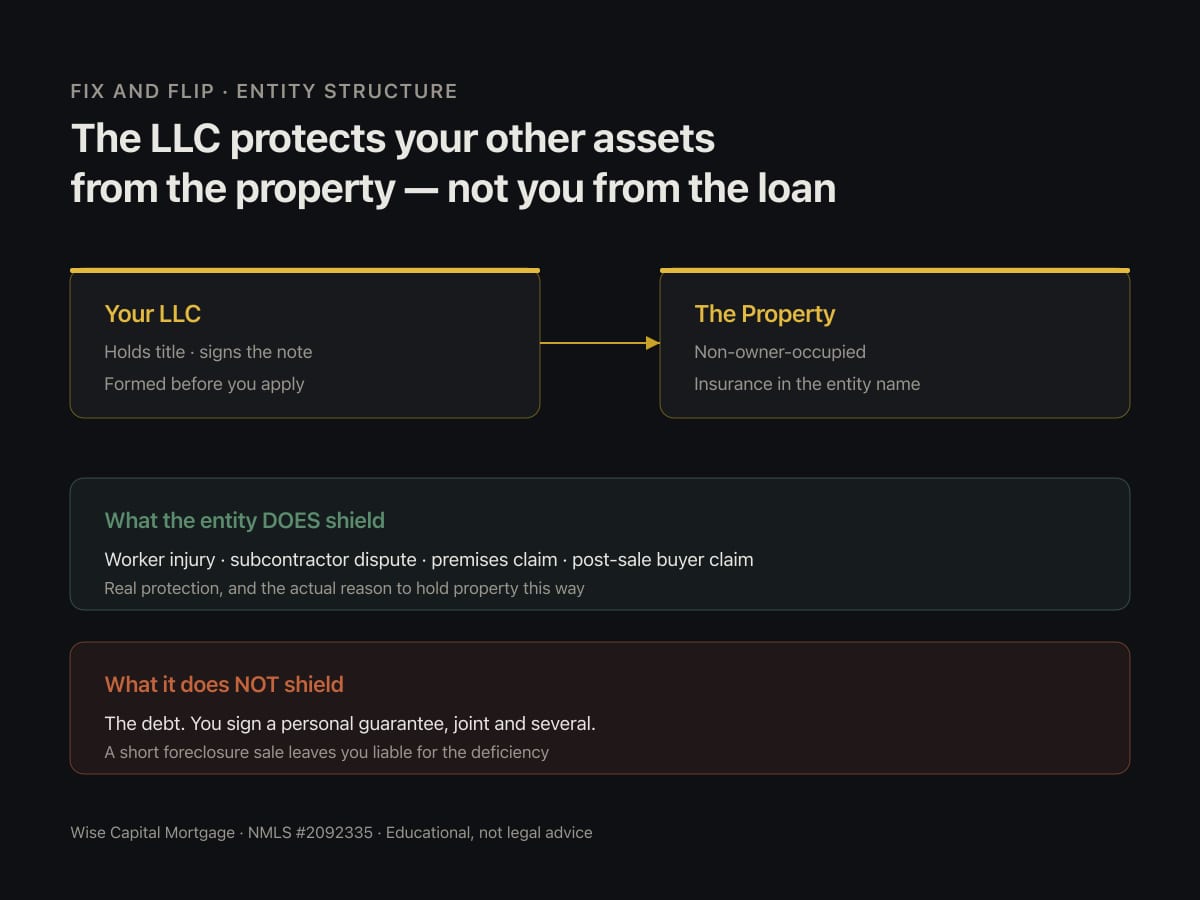
Entity structure diagram for a fix and flip project showing the LLC holding title with a personal guarantee and separate tax treatment
Fix & Flip
Fix and Flip in an LLC: Dealer Status and the Tax Problem
Flipping in an entity is standard for lending, but the tax treatment differs sharply from rentals. Dealer status, self-employment tax, and what it changes.
Appraisal comparison grid showing subject property adjusted against three comparable sales to derive after repair value
Fix & Flip
ARV: How Appraisers Set It, and How to Contest a Low One
How after repair value is actually determined, why your receipts do not appear in it, and the reconsideration process that occasionally works.
BRRRR cycle diagram showing capital deployed at purchase and recovered at refinance with the equity spread required at each stage
Bridge
The BRRRR Method: The Margin Math, and Three Ways It Fails
BRRRR only works when forced appreciation exceeds total cost by enough to refinance out. The spread you need, and the three ways deals break.
Timeline showing a bridge loan spanning the gap between a property acquisition and a pending sale or permanent refinance
Bridge
Bridge Loans for Investors: Solving Timing, Not Condition
Bridge financing solves a timing gap, not a condition problem. When it beats hard money, what it costs, and the exit risk that defines it.
Seven day hard money closing timeline showing appraisal, title, insurance and document preparation running in parallel
Hard Money
Closing Hard Money in 7 Days: What Actually Controls the Clock
Seven-day closings are real but conditional. The four things that actually gate the timeline, and the preparation that makes speed possible.
Central Texas flip project cost breakdown showing property tax, insurance, permit and foundation line items against a renovation budget
Local
Fix and Flip Loans in Texas: The Local Cost Lines That Decide Deals
Texas flip economics turn on property tax, insurance, foundation risk and permit timelines. What each one costs and how to budget them properly.
Deal screening worksheet showing eight underwriting checks applied to a rental and a flip scenario side by side
Deal Desk
How to Stress-Test a Deal Before You Send It to a Lender
The eight checks a deal should survive before it reaches underwriting, the four inputs to stress, and what a decline is usually telling you.
Austin, Texas skyline at sunset — Austin mortgage rates 2026 | Wise Capital Mortgage
Rates
Austin Mortgage Rates in 2026: What Buyers Should Actually Expect
Where 30-year fixed rates sit today, why, and how to plan around them.
First-time home buyer holding keys — down payment assistance in Austin, Texas | Wise Capital Mortgage
First-Time Buyers
Down Payment Assistance Programs for Austin First-Time Buyers
TSAHC, TDHCA and City of Austin programs that can cut your upfront cost.
Couple reviewing FHA and conventional loan paperwork | Wise Capital Mortgage, Austin TX
Loan Comparison
FHA vs. Conventional: Which Loan Is Right for You?
A side-by-side breakdown of down payment, credit and mortgage insurance.
Austin residential neighborhood with downtown skyline — how much home can you afford | Wise Capital Mortgage
Affordability
How Much Home Can You Afford in Austin at Today's Rates
Real income-to-payment math for $400K-$550K Austin purchases.
DSCR Loans Explained: Buying Rental Property Without W-2 Income | Wise Capital Mortgage
Investors
DSCR Loans Explained: Buying Rental Property Without W-2 Income
How the debt service coverage ratio qualifies a property, not a paycheck.
Fix and Flip Financing 101: How Hard Money Loans Work | Wise Capital Mortgage
Investors
Fix and Flip Financing 101: How Hard Money Loans Work
Speed, terms and exit strategy for asset-based investor loans.

More Guides

For Real Estate Investors
Creative Financing Explained

Educational overviews of structures active in the Texas market. Wise Capital Mortgage does not originate or facilitate these transactions.
Buying Basics
Loan Programs
HOMEFRONT, Wise Capital Mortgage's first-time and conventional home buyer hero, standing before a two-story suburban home at golden hour
Conventional
Conventional Loans Explained: Rates, Down Payments and 2026 Requirements
2026's conforming loan limit hits $832,750. Down payment tiers, credit minimums and rates, explained plainly.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, in front of a modest starter home at sunrise
FHA
FHA Loan Requirements 2026: Credit, Down Payment and MIP Explained
Still 580 credit and 3.5% down in 2026. The full score, DTI and mortgage insurance breakdown.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing beside a home with an American flag on the porch
VA
VA Loan Requirements: Eligibility, Entitlement and the Funding Fee
0% down, no monthly PMI. Full eligibility, credit and funding fee requirements for 2026.
THE RATE SLAYER, Wise Capital Mortgage's refinance hero, breaking a chain of high interest rates
Refinance
When to Refinance Your Mortgage
Closing costs divided by monthly savings. The break-even math before you refinance.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, reviewing a pre-approval file at his desk
Purchase Process
The Mortgage Pre-Approval Process
What lenders verify, and how to strengthen your offer letter.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing in front of a rural Texas home
USDA
USDA Loan Requirements: Income Limits, Eligible Areas and How It Works
0% down for eligible rural and suburban areas. The income limits and eligibility map, explained.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, reviewing household paperwork at a kitchen table in a Texas home
USDA
USDA Income Limits 2026: How Household Size Changes Eligibility
Two income tiers, not one per household size. How deductions and extra occupants move the ceiling.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing at a fork in a rural Texas road beneath two signposts representing two loan paths
USDA
USDA Guaranteed vs Direct Loan: What's the Difference
Private lender or USDA itself. How the income tiers, rate structure and timeline split.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing between two mailboxes on a rural Texas road representing a choice between two loan programs
USDA
USDA vs FHA: Which Zero-to-Low-Down Loan Costs Less
0% down beats 3.5% down, but the fee math doesn't always follow. The real cost comparison.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, reviewing a closing cost worksheet at a kitchen table in a rural Texas home
USDA
USDA Loan Closing Costs and the Guarantee Fee
2-5% in ordinary closing costs, plus a 1% upfront guarantee fee most buyers finance in.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, inspecting the foundation and roofline of a rural Texas home with a clipboard
USDA
USDA Property Requirements: What Can Disqualify a Home
Passing the eligibility map isn't enough. The condition, use and acreage rules that can still sink a USDA appraisal.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing in front of a large luxury home
Jumbo
Jumbo Loan Requirements 2026: Credit, Reserves and Down Payment
Above $832,750. The typical credit, reserve and down payment ranges lenders use.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, reviewing a rate comparison chart in front of a large luxury home at dusk
Jumbo
Jumbo Loan Rates vs Conventional: Why the Spread Isn't What You Think
The spread ran near zero through 2026 and flipped direction more than once. What actually moves it.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, stacking coins beside a model of a large luxury home to represent down payment tiers
Jumbo
Jumbo Loan Down Payment: How Much Do You Really Need
10% to 20% is the common range, but loan size and property type move the real minimum.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, reviewing a stack of financial statements at a desk with a large luxury home visible through the window behind him
Jumbo
Jumbo Loan for Self-Employed Borrowers: Alternative Documentation Options
Bank statement, P&L only and asset depletion, the three paths around standard tax-return underwriting.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, reviewing bank statements at a desk
Bank Statement
Bank Statement Loan Requirements
Qualify on 12-24 months of deposits instead of tax returns.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, standing at a fork between a bank building and a row of open lender doors
Choosing a Lender
Mortgage Broker vs. Direct Lender: Which Should You Choose?
A broker shops dozens of lenders. A bank only offers its own menu. Here's the real difference.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, handing over a set of house keys
Choosing a Lender
Best Mortgage Lender for First-Time Homebuyers
Program access, DPA compatibility and pre-approval accuracy, not the lowest advertised rate.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, comparing several rate quotes side by side
Choosing a Lender
How to Actually Find the Lowest Mortgage Rate
The advertised rate and your real quote are rarely the same number. Here's why.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, checking items off a list on a clipboard
Choosing a Lender
Questions to Ask a Mortgage Lender Before You Choose One
The direct checklist: rate, fees, timeline, compensation and the questions that expose a weak fit.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, reviewing a mortgage insurance statement at a kitchen table
FHA
FHA Mortgage Insurance (MIP) Explained: Upfront, Annual and How to Drop It
1.75% upfront, plus an annual premium most borrowers never see broken out by LTV. The full schedule and how to remove it.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, holding a map of Texas counties in front of a row of homes
FHA
2026 FHA Loan Limits by Texas County
$541,287 in most counties, $571,550 around Austin. The county-by-county breakdown.
HOMEFRONT, Wise Capital Mortgage's first-time and conventional home buyer hero, reviewing down payment options with a young couple at a kitchen table
Conventional
Conventional Loan Down Payment Options: 3% vs 20% and When PMI Makes Sense
3% gets you in sooner with PMI. 20% removes it from day one. The break-even math that decides which wins.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, standing beside a fixer-upper home with scaffolding and renovation materials
FHA
FHA 203(k) Renovation Loan: Buying a Fixer-Upper With One Loan
Up to $75,000 in repairs rolled into one mortgage. How Limited and Standard 203(k) differ, and who qualifies.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, reviewing paperwork at a desk with a calendar in the background
FHA
FHA Loan After Bankruptcy or Foreclosure: Waiting Periods Explained
2 years after Chapter 7, 3 after foreclosure, sometimes sooner. The exact waiting periods and the exception that shortens them.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, reviewing a refinance paperwork folder with a homeowner on their front porch
FHA
FHA Streamline Refinance: How It Works and Who Qualifies
No appraisal, often no credit pull. The net tangible benefit test and 210-day seasoning rule that decide who actually qualifies.
HOMEFRONT, Wise Capital Mortgage's first-time and conventional home buyer hero, reviewing a mortgage statement with a homeowner at a kitchen table
Conventional
How to Remove PMI From a Conventional Loan
PMI comes off automatically at 78% LTV. The exact steps to drop it sooner at 80%, through an appraisal, or by refinancing.
HOMEFRONT, Wise Capital Mortgage's first-time and conventional home buyer hero, standing before a map of Texas counties at golden hour
Conventional
2026 Conforming Loan Limits by Texas County
$832,750 in every single Texas county. Why the conforming limit doesn't vary the way FHA's does.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing beside a ledger of stacked savings tiers in front of a large luxury home
Jumbo
Jumbo Loan Reserve Requirements: How Many Months Lenders Want
Six to twelve months of PITI is typical, more above $2 million. What counts as a reserve and how the tiers work.
HOMEFRONT, Wise Capital Mortgage's home buyer hero, standing beside a tall stack of coins and financial ledgers transforming into a glowing income chart, with a large home in the background
Jumbo
Asset Depletion Loans: Qualifying for a Jumbo Without W-2 Income
No paycheck, no tax return. How lenders turn retirement accounts and investments into qualifying income instead.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, standing in front of a manufactured home on a landscaped Texas lot
FHA
FHA Loan for Manufactured and Mobile Homes in Texas
3.5% down works on a manufactured home too, if it clears the foundation and titling rules. What qualifies and what doesn't.
HOMEFRONT, Wise Capital Mortgage's first-time home buyer hero, reviewing a home inspection checklist on the porch of a Texas starter home
FHA
FHA Appraisal Requirements: What Inspectors Flag
Roof, electrical, peeling paint, missing handrails. The exact items HUD requires an appraiser to flag before closing.
HOMEFRONT, Wise Capital Mortgage's purchase loan hero, reviewing a closing disclosure with a veteran homebuyer at a kitchen table
VA
VA Funding Fee Explained: 2026 Rates and Who's Exempt
1.25% to 3.3% of the loan amount, unless you're exempt. How to verify your fee and claim a refund if a disability rating comes through late.
HOMEFRONT, Wise Capital Mortgage's purchase loan hero, standing between two paths outside a Texas home representing a VA loan and a conventional loan
VA
VA Loan vs Conventional: When Zero Down Beats a Bigger Down Payment
0% down with a one-time fee, or a bigger down payment with monthly PMI. Which one actually costs less depends on the numbers.
HOMEFRONT, Wise Capital Mortgage's VA loan hero, reviewing a loan timeline with a veteran homeowner on a porch
VA
VA Streamline Refinance (IRRRL) Explained
The 210-day, six-payment seasoning clock, the occupancy rule, and what closing actually looks like for a VA IRRRL.
HOMEFRONT, Wise Capital Mortgage's VA loan hero, standing between two house keys representing a veteran's first and second VA loan
VA
Second-Tier VA Entitlement: Using Your VA Loan More Than Once
Keep loan one and buy again, or sell and restore full entitlement first. The funding fee and DTI math that decides it.
HOMEFRONT, Wise Capital Mortgage's VA loan hero, standing before a large two-story home set back from the street at dusk
VA
VA Jumbo Loans: Financing Above the Conforming Limit With No Down Payment
Full entitlement still means 0% down above $832,750. What changes is the lender's file, not a government loan limit.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, counting through a stack of bank statements at a desk
Bank Statement
How Many Months of Bank Statements Do You Need for a Mortgage
Most programs count 12 or 24 months of deposits. Which one fits depends on how your income moved, not which sounds easier.
HOMEFRONT, Wise Capital Mortgage's first-time and conventional home buyer hero, standing before a lakeside second home at sunset
Conventional
Conventional Loan for a Second Home: Requirements and Rate Differences
10% down, not 3%. The occupancy rules, reserve requirements and pricing gap that separate a second home from a primary residence.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, standing between two illuminated ledgers representing personal income and rental income
Bank Statement
Bank Statement Loan vs DSCR Loan: Which One Fits Your Situation
One qualifies you. The other qualifies the property. The occupancy question that decides which program actually applies.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, reviewing a stack of 1099 tax forms at a desk
Bank Statement
1099 Mortgage Loans: Qualifying on Contractor Income
A much smaller expense factor than a bank statement loan. Who actually comes out ahead qualifying straight off 1099 forms.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, reviewing a profit and loss statement at a desk
Bank Statement
P&L Only Mortgage Loans: Qualifying Without Bank Statements
One CPA-signed document, no bank statements reviewed at all. Where this program beats a standard bank statement loan, and where it doesn't.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, standing over a pricing grid of stacked rate adjustment sheets
Bank Statement
Bank Statement Loan Rates: What Self-Employed Borrowers Actually Pay
Credit score, down payment and statement period each move the price. The factors that set the real gap above conventional.
CAPTAIN EQUITY, Wise Capital Mortgage's bank statement and investment loan hero, stacking reserve fund ledgers beside a down payment chart
Bank Statement
Bank Statement Loan Down Payment and Reserve Requirements
10% to 20% down plus 3 to 12 months of reserves. How credit, loan-to-value and property type move both numbers.