DSCR loans that qualify the property, not your paycheck.
No tax returns. No W-2s. No personal debt-to-income cap. If the rent covers the payment, the deal qualifies — and you can close in your LLC.
DSCR loans for investors nationwide, diagnosed in 10 seconds
Every DSCR loan starts with one check: does the rent cover the payment? The DSCR Doctor scans a rental property and reads the numbers a DSCR lender looks at first.
What the DSCR Doctor finds
- Rent: $4,500 a month in the example.
- PITIA: $2,800 a month. That is principal, interest, taxes, insurance and any HOA dues.
- DSCR: $4,500 ÷ $2,800 ≈ 1.61. A ratio at or above 1.0 means the rent covers the payment, and 1.25 or higher is where the best pricing typically starts.
- Cash flow: about $1,700 a month left after the payment.
The math is the same in every state we lend in. What changes from market to market is the property tax and insurance inside the PITIA, which is why the same rent can clear the bar in one state and fall short in another. Test your own property with the DSCR calculator, read the full DSCR loan requirements, or see how DSCR loans work nationwide.
Does your deal qualify? Find out right now.
Enter the property's numbers. We'll calculate your debt service coverage ratio live — the exact figure a DSCR underwriter looks at first.
Estimates only, based on a 30-year fixed amortization. Property tax and insurance vary widely by state and county, so enter your property’s actual figures. Not a rate quote or lending commitment.
{{ verdictNote }}
Free · No credit pull · Appraisal reimbursed for our first 100 clients
Conventional financing has a ceiling. DSCR doesn't.
DSCR vs. conventional investor loans
Conventional often prices lower if you can document income and stay under the limits. Past that point, DSCR is the only road that keeps going.
Price My Deal Both Ways| DSCR Loan | Conventional Investor | |
|---|---|---|
| Qualifies on | Property rental income | Your personal income |
| Tax returns required | No | Yes — two years |
| Personal DTI counted | No | Yes |
| Financed property cap | Generally none | Typically 10 |
| Close in an LLC | Commonly allowed | Generally not |
| Typical down payment | 20–25% | 15–25% |
| Short-term rental income | Often counted | Rarely counted |
Property types that qualify
Serving rental property investors across the country — purchases, rate-and-term refinances and cash-out refinances alike, on properties in most states. See our guide to DSCR loans nationwide, or send the property address and we will confirm availability first.
Deal to closing in four moves
Investors don't need hand-holding. They need accurate numbers early enough to act on them.
Start Step OneThat's genuinely all we need to run your DSCR and give you a real read on terms — usually same day.
As a broker we price your file across wholesale DSCR lenders, compare prepay structures, and flag when conventional would actually serve you better.
The appraiser's market rent analysis confirms the income your ratio is built on. Short-term rentals get underwritten on the right data, not long-term comps.
Entity docs handled up front so vesting never becomes the thing that delays your closing.
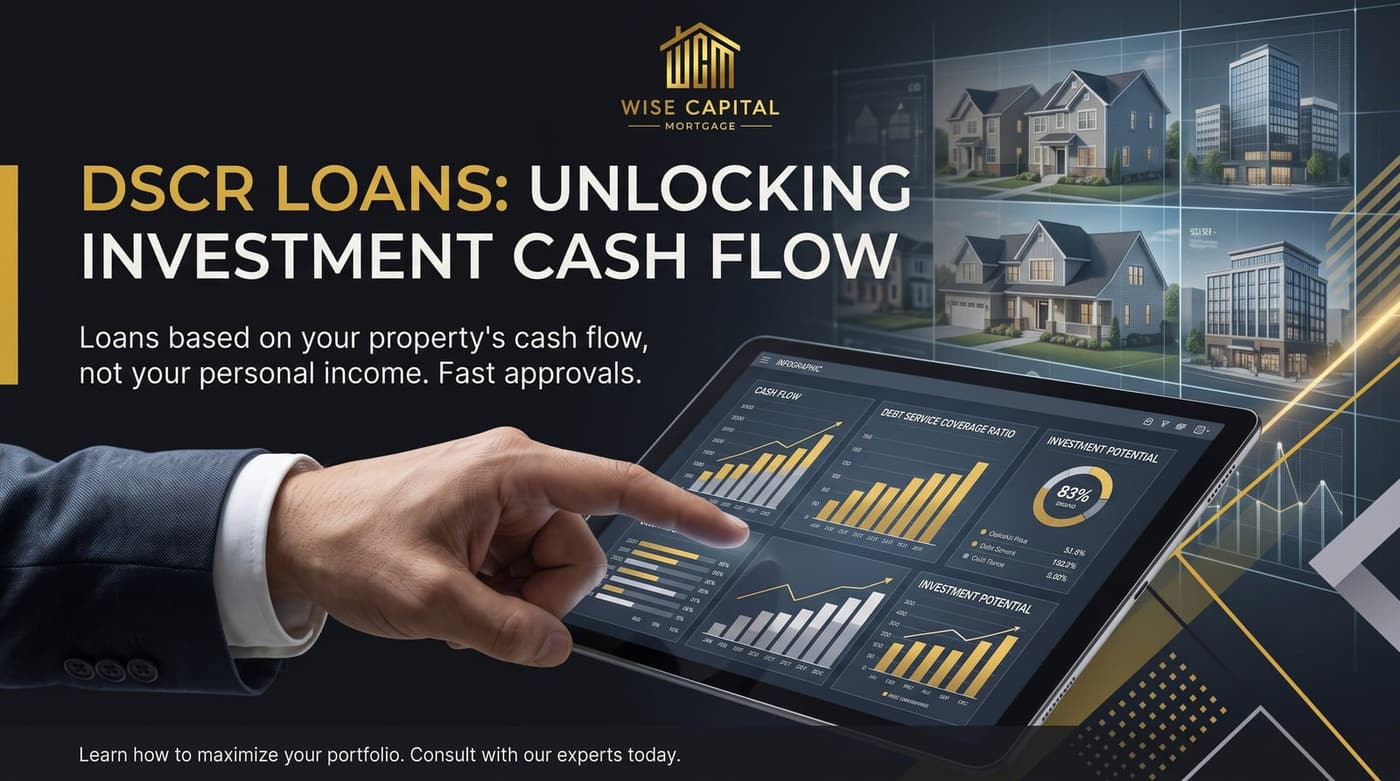
How the debt service coverage ratio is calculated
Your DSCR is the property's gross monthly rent divided by its total monthly payment — principal, interest, taxes, insurance and any HOA dues. A property renting for $2,400 with a $2,000 total payment carries a DSCR of 1.2, meaning it produces 20% more income than the debt requires. Most DSCR lenders price their best terms at 1.25 and above, still approve comfortably at 1.0, and some will go below 1.0 in exchange for a larger down payment.
DSCR loan terms investors should expect
Down payments generally start around 20-25%, credit score minimums commonly sit between 620 and 680, and rates run above comparable owner-occupied financing because investment property carries more risk for the lender. Many DSCR programs include a prepayment penalty for the first three to five years, so if you plan to sell or refinance quickly, ask about the prepay structure before you lock.
Closing in an LLC and scaling your portfolio
Because DSCR loans are underwritten on the property rather than your personal debt-to-income ratio, most lenders allow you to close in the name of an LLC and place no hard cap on the number of DSCR loans you hold. That combination is why investors who hit Fannie Mae's financed-property limit move to DSCR financing to keep acquiring — each new deal is judged on its own numbers.
Buying a property that needs work first
If the property isn't rentable yet, the standard play is to acquire it with a fix and flip or hard money loan, renovate, lease it, then refinance into a DSCR loan on the stabilized rent. That's the refinance step of the BRRRR strategy, and it's how portfolios compound without fresh outside capital. We structure the front-end loan with that exit already in view.
DSCR loan FAQ
Send us one address. We'll tell you if it flies.
Real DSCR math, real terms from our lender panel, and an honest answer on whether conventional would serve you better — before you're under contract.
Keep Reading
Book a free DSCR loan strategy call
Tell us about your property or portfolio. We will walk through your DSCR, leverage, closing in an LLC and what lenders will look at.
- 30 minutes, by video (Google Meet) or phone
- Free, with no obligation to apply
- Pricing, leverage and an LLC-ready plan for your deal
- You talk to a licensed loan officer, not a call center
Pick a time that works for you
Choose a slot on the calendar and you will get a confirmation by email. No obligation, no pressure.
Prefer to talk now? Call 512-588-2771 · open the calendar in a new tab.