VA home loans in Texas with 0% down for those who served
You earned a home loan benefit. We help veterans, active-duty service members, Guard and Reserve members, and surviving spouses use it, with no down payment and no monthly mortgage insurance.
Free, no obligation · or call 512-588-2771
You served. Using your benefit should not be a battle.
Plenty of eligible veterans never use their VA benefit because of a few myths and a lot of paperwork anxiety.
You earned this benefit. Our job is to make it easy to use.
From first call to closing, in four steps
Tell us your situation
A 30-minute call or a short online application: income, savings, credit, and the kind of property you want.
Get a real plan
We compare your options across programs and lenders, explain the costs in plain English, and tell you if anything is worth fixing first.
Get approved
With your documents in hand, we move your file to underwriting and issue the approval you need to move forward with confidence.
Close with confidence
We manage the file through appraisal, underwriting and closing, and keep you updated at every stage.
One of the strongest home loan benefits there is
Zero down for eligible borrowers
Buy without a down payment and keep your savings for moving, furniture and a rainy-day fund.
No monthly mortgage insurance
VA loans do not carry monthly PMI, which can save a few hundred dollars every month compared with a low-down-payment FHA or conventional loan.
Flexible guidelines
VA underwriting is built around military families, with flexible credit and debt-to-income standards.
Limits on closing costs
VA caps certain lender fees, and sellers can contribute toward your closing costs.
The IRRRL refinance
The Interest Rate Reduction Refinance Loan is a streamlined way to lower the rate on an existing VA loan.
A benefit you can reuse
Use it more than once, and in many cases get it restored. We check your remaining entitlement.
Not sure what you qualify for? We will find out.
Most Certificates of Eligibility take minutes. We confirm your entitlement and show you your real numbers.
Who is eligible for a VA loan?
Eligibility depends on your service history. Meeting the service requirement opens the door to the program, but a lender still reviews your credit, income and debt-to-income ratio before approving a loan.
- Veterans: 90 consecutive days of active duty during wartime, or 181 days during peacetime.
- Active-duty members: the same minimum while still serving.
- National Guard and Reserve: six creditable years of service. Some qualify sooner after a federal activation or a service-connected discharge.
- Surviving spouses: of a service member who died in the line of duty or from a service-connected disability.
- Discharge: general or honorable is standard, and some other discharges may still qualify.
Getting your Certificate of Eligibility (COE)
The COE confirms your service history and remaining entitlement. There are three ways to get one, and the first is the easiest.
| How | What you need | Typical speed |
|---|---|---|
| Through us (a VA-approved lender) | Your service details. We use the lender system. | Usually minutes |
| A VA.gov account | Complete service records already on file | Varies |
| By mail (VA Form 26-1880) | A DD214 or statement of service | Longer |
Veterans typically need a DD214. Active-duty members need a statement of service signed by a commander, adjutant or personnel officer. Surviving spouses usually submit a DD214, proof of marriage and a VA determination of service-connected death. The COE confirms eligibility, not loan approval.
The VA funding fee, explained
Most VA borrowers pay a one-time funding fee that supports the program, and it can be financed into the loan instead of paid at closing. Veterans who receive compensation for a service-connected disability are typically exempt.
The amount depends on your down payment and whether you have used your benefit before, so we show you the exact figure up front. See the full breakdown in our VA loan requirements guide, or the advantages in the VA loan benefits guide.
Ready to see your VA numbers?
A quick call gets you a straight answer on payment, funding fee and cash to close.
VA vs. FHA vs. conventional
If you are eligible, VA usually wins on up-front cost. Here is the comparison.
| VA | FHA | Conventional | |
|---|---|---|---|
| Minimum down | 0% | 3.5% (580+ credit) | As low as 3% |
| Monthly mortgage insurance | None | Yes (upfront + annual) | PMI until about 78–80% loan-to-value |
| Who qualifies | Eligible service members and spouses | Most buyers | Most buyers |
| Occupancy | Primary residence | Primary residence | Primary, second home or investment |
We run every option on your numbers, so you can see the real monthly payment and cash to close side by side.
Serving Central Texas military communities
Central Texas is home to a large military community, including Fort Cavazos near Killeen and Temple, and VA financing is one of the most valuable benefits available to those families.
We help active-duty members, veterans and spouses buy and refinance across Texas. Explore our local pages for Killeen and Temple.
Refinancing with a VA loan
VA offers the IRRRL to lower your rate on an existing VA loan with less paperwork, and a VA cash-out refinance if you want to use your equity. See our refinance options to compare.
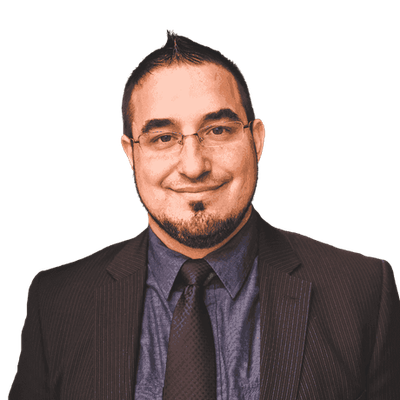
Meet your VA Loans loan officer
Matthew MontsDeOca is an independent mortgage broker based in Austin — Texas’s state capital — licensed to help buyers and homeowners across the entire state, from Houston and San Antonio to Dallas-Fort Worth and everywhere between. Because Wise Capital shops a panel of lenders instead of selling one bank’s products, you get advice on which program actually fits, including when this one is not the right answer.
Your questions, answered
Who can get a VA loan?
Do I need a down payment for a VA loan?
Is there a VA funding fee?
Is there monthly mortgage insurance on a VA loan?
What is a Certificate of Eligibility?
Can I use my VA loan benefit more than once?
Can I use a VA loan to refinance?
Can I buy a rental or second home with a VA loan?
Book a free 30-minute call
Not ready to apply? Talk it through first. We will look at your numbers and tell you honestly what your best move is.
- 30 minutes, by video (Google Meet) or phone
- Free, with no obligation to apply
- A clear next step, whether that is applying now or fixing one thing first
- You talk to a licensed loan officer, not a call center
Pick a time that works for you
Choose a slot on the calendar and you will get a confirmation by email. No obligation, no pressure.
Prefer to talk now? Call 512-588-2771 · open the calendar in a new tab.
Let us show you what you qualify for.
Check your options in a few minutes, or book a quick call and we will walk you through it.
Or call 512-588-2771 · Free, no obligation
Keep learning, in plain English
Other loan programs
Wise Capital Mortgage is not affiliated with, endorsed by, or acting on behalf of the U.S. Department of Veterans Affairs or any government agency. This is not an official government advertisement. VA-guaranteed loans are made by private lenders.
*0% down payment is available to eligible borrowers with sufficient entitlement. Most VA loans require a one-time funding fee unless exempt, and the property must be your primary residence and meet VA minimum property requirements. Credit, income and underwriting requirements apply. Interest rates and APR depend on your credit profile, loan amount and market conditions. Ask us for a personalized Loan Estimate.
Wise Capital Mortgage, LLC · 5900 Balcones Drive #23333, Austin, TX 78731 · NMLS #2092335 · Equal Housing Lender. Matthew MontsDeOca, NMLS #1034513. This page is for general information and is not a commitment to lend or an offer of credit. Loan programs, eligibility, terms and rates are subject to change and to underwriting approval. You can verify our licensing at the NMLS Consumer Access website, nmlsconsumeraccess.org.