Down payment assistance in Texas worth 3–5% of your loan
State, city and lender programs can cover part of your down payment and closing costs as a grant or a deferred second lien. We check every one against your income, location and buyer status, for free.
Free, no obligation · or call 512-588-2771

The down payment is the real wall.
For most buyers, the payment is not the problem. Saving the cash is.
Often you can stack programs, and the result is a purchase with far less cash to close than the 3.5% or 5% you planned for.
From first call to closing, in four steps
Tell us your situation
A 30-minute call or a short online application: income, savings, credit, and the kind of property you want.
Get a real plan
We compare your options across programs and lenders, explain the costs in plain English, and tell you if anything is worth fixing first.
Get approved
With your documents in hand, we move your file to underwriting and issue the approval you need to move forward with confidence.
Close with confidence
We manage the file through appraisal, underwriting and closing, and keep you updated at every stage.
Less cash to close, same dream home
Real money toward your purchase
Assistance can cover a meaningful share of your down payment and closing costs.
Stacks with your loan
Pair it with FHA, VA, USDA or a conventional program that allows it.
Hero programs
Homes for Texas Heroes serves teachers, firefighters, EMS, police, corrections officers and veterans.
State and local
Statewide programs, plus city-specific help in many Texas markets — we check what applies to your address.
Honest side-by-side
We quote your loan with and without assistance, so you choose with numbers, not a rumor.
Early beats late
Funds are limited and programs pause and reopen, so checking early opens more paths.
Could you qualify for assistance?
One conversation tells you which programs fit your income, location and buyer status.
The programs Texas buyers actually use
Programs and funding change, so we confirm what is open for your file before you plan around any of them. The three below are statewide; most major Texas cities also run their own local program on top — Austin’s is shown as one example, and we check what your own city offers.
Home Sweet Texas Home Loan
3% to 5% of the loan amount as a non-repayable grant or a deferred 0% second lien repaid only on sale, refinance or payoff. Pairs with FHA, VA, USDA and conventional HFA financing. Open to any profession within income limits.
Homes for Texas Heroes
The same assistance structure, reserved for teachers, firefighters, EMS, police, corrections officers and veterans. Usually the first program we check for anyone who serves.
My First Texas Home
A below-market first mortgage paired with down payment and closing cost assistance for eligible first-time and veteran buyers statewide.
Austin Housing Finance Corporation
Local assistance for buyers purchasing inside Austin city limits, sometimes with deeper support for lower-income households, layered on top of state programs. Houston, Dallas, San Antonio and other cities run similar local programs — tell us where you are buying and we will check.
Three tests usually decide it
Purchase price caps and property-type rules also apply and vary by program. Rather than sending you to a state website to decode it, we run your actual file against every program you might be eligible for.
- Income: your household income relative to the limit for your county and household size. These limits are higher than most buyers assume.
- First-time buyer status: nearly every program defines it as not having owned a home in the previous three years. It is waived for veterans and for purchases in designated targeted areas.
- Homebuyer education: most programs require an approved course before closing.
Find your programs in one conversation.
We check state, city and lender assistance against your income, location and buyer status.
Grant or second lien: know which one you are getting
A grant never has to be repaid. A deferred second lien carries no interest and no monthly payment, but comes due when you sell, refinance or pay off the home. Both are good outcomes. They are simply different, and you should know which one you signed before closing.
Does assistance mean a worse loan? Sometimes there is a small rate trade-off, and sometimes there is none. It depends on the program and your credit profile. We quote both scenarios side by side in writing, including total cost over the years you plan to own the home.
Can you stack programs?
The result can be a purchase where your total cash to close is dramatically smaller than the 3.5% or 5% you were budgeting for. See how these pair with FHA loans, VA loans and USDA loans, or read our down payment assistance in Austin guide.
Timing decides your options
Buyers who check eligibility early have far more paths available. If you are even considering a purchase in the next twelve months, the eligibility check is free and takes one conversation.
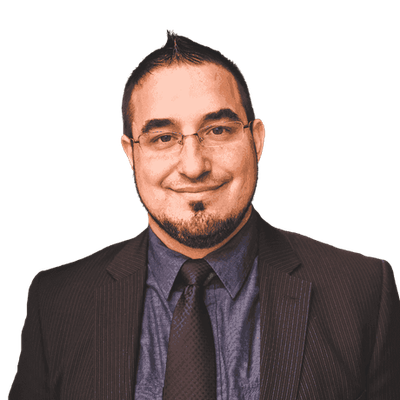
Meet your Down Payment Assistance loan officer
Matthew MontsDeOca is an independent mortgage broker based in Austin — Texas’s state capital — licensed to help buyers and homeowners across the entire state, from Houston and San Antonio to Dallas-Fort Worth and everywhere between. Because Wise Capital shops a panel of lenders instead of selling one bank’s products, you get advice on which program actually fits, including when this one is not the right answer.
Your questions, answered
What is down payment assistance?
How much assistance can I get?
Do I have to be a first-time buyer?
Are there income limits?
Can I use assistance with FHA, VA or USDA?
Is there a catch with a second lien?
Will assistance give me a worse interest rate?
Are there programs for teachers and first responders?
Book a free 30-minute call
Not ready to apply? Talk it through first. We will look at your numbers and tell you honestly what your best move is.
- 30 minutes, by video (Google Meet) or phone
- Free, with no obligation to apply
- A clear next step, whether that is applying now or fixing one thing first
- You talk to a licensed loan officer, not a call center
Pick a time that works for you
Choose a slot on the calendar and you will get a confirmation by email. No obligation, no pressure.
Prefer to talk now? Call 512-588-2771 · open the calendar in a new tab.
Let us show you what you qualify for.
Check your options in a few minutes, or book a quick call and we will walk you through it.
Or call 512-588-2771 · Free, no obligation
Keep learning, in plain English
Other loan programs
Wise Capital Mortgage is not affiliated with TSAHC, TDHCA, the City of Austin or any government agency. Program names are used to describe publicly available programs. Down payment assistance programs have eligibility requirements, including income and purchase price limits, may require homebuyer education and a specific first mortgage, may change or pause funding without notice, and may carry a deferred second lien. Interest rates and APR depend on your credit profile, loan amount and market conditions. Ask us for a personalized Loan Estimate.
Wise Capital Mortgage, LLC · 5900 Balcones Drive #23333, Austin, TX 78731 · NMLS #2092335 · Equal Housing Lender. Matthew MontsDeOca, NMLS #1034513. This page is for general information and is not a commitment to lend or an offer of credit. Loan programs, eligibility, terms and rates are subject to change and to underwriting approval. You can verify our licensing at the NMLS Consumer Access website, nmlsconsumeraccess.org.