USDA home loans in eligible Texas areas with 0% down
Zero-down financing for eligible homes just outside major metros statewide, with lower mortgage costs than FHA. More of Texas qualifies than most buyers expect, and we check any address for free.
Free, no obligation · or call 512-588-2771

Think USDA means living on a farm?
It is one of the most overlooked loans in Texas, mostly because of what the name suggests.
More suburban and small-town communities qualify today than a few years ago, near every major Texas metro. The only way to know is to check the address.
From first call to closing, in four steps
Tell us your situation
A 30-minute call or a short online application: income, savings, credit, and the kind of property you want.
Get a real plan
We compare your options across programs and lenders, explain the costs in plain English, and tell you if anything is worth fixing first.
Get approved
With your documents in hand, we move your file to underwriting and issue the approval you need to move forward with confidence.
Close with confidence
We manage the file through appraisal, underwriting and closing, and keep you updated at every stage.
The lowest-cost way into a home, when the address fits
No down payment
USDA finances the full purchase price, one of only two zero-down programs for civilian buyers alongside VA.
Lower mortgage costs than FHA
Instead of traditional mortgage insurance, USDA charges an upfront guarantee fee and a smaller annual fee, which is generally lower than FHA insurance.
Flexible credit
USDA does not publish a hard minimum score. Most lenders look for roughly 640 to use automated underwriting.
Closer than you think
Eligible areas often sit just 30 to 40 minutes outside any major Texas metro, not out in the country.
Sellers can help
Sellers are allowed to contribute toward your closing costs, and some eligible costs can be rolled into the loan when the appraisal supports it.
Streamlined refinance
Existing USDA borrowers have streamlined refinance options when rates drop.
Wondering if your dream address qualifies?
Send it to us. We confirm USDA eligibility and your income qualification at no cost, before you write an offer.
How USDA eligibility works
USDA loans have two eligibility tests. The first is the property. It must sit inside a USDA-designated rural or suburban area. The second is you. Your total household income must fall under the limit for your county and family size.
The location test surprises many buyers. A large share of communities within a 30 to 45 minute drive of Austin qualify, including areas around Hutto, Elgin, Manor and Lockhart and parts of Bastrop, Caldwell and Hays counties.
- Location: based on the property address, not how it looks.
- Income: total household income counts, not just the borrowers on the loan.
- Occupancy: it must be your primary residence.
- Maps change: an address that did not qualify a few years ago may qualify now, or the reverse.
USDA vs. FHA vs. conventional
If the address qualifies, USDA often has the lowest monthly cost. Here is how they compare.
| USDA | FHA | Conventional | |
|---|---|---|---|
| Minimum down | 0% | 3.5% (580+ credit) | As low as 3% |
| Mortgage insurance | Upfront guarantee fee + small annual fee | Upfront + annual premium | PMI until about 78–80% loan-to-value |
| Location rule | USDA-eligible area only | None | None |
| Income limit | Yes, by county and household size | No | No |
| Occupancy | Primary residence | Primary residence | Primary, second home or investment |
We compare every program that fits and show you the real payment and cash to close.
Zero down, with a few things to know
A USDA loan finances the full purchase price, so you can buy without a down payment. You will still have closing costs, although sellers can contribute toward them and some eligible closing costs can be rolled into the loan when the appraised value supports it.
Because USDA uses a guarantee fee instead of traditional mortgage insurance, a USDA loan often produces a lower monthly payment than FHA on the same home, assuming the address and income both qualify. Read the details in our USDA loan requirements guide.
Find out in one conversation.
Tell us the address and your household details. We will confirm eligibility and show you the payment.
One example of how this plays out: Austin
Eligibility is decided address by address, and growing communities just outside any major metro’s urban core are where buyers most often find a USDA fit — this holds true around Houston, Dallas-Fort Worth and San Antonio just as it does around Austin. See our guide to USDA loan eligibility in the Austin suburbs as one worked example, or send us any address anywhere in Texas and we’ll check it for free.
USDA credit and income guidelines
Income limits are based on total household income and vary by county and household size. Because both tests are specific to your address and household, the fastest path is simply to send us the property address and your household details. We confirm eligibility at no cost before you write an offer.
Short on cash for closing costs? Pair USDA with down payment assistance in Texas where it fits.
Meet your USDA loan officer
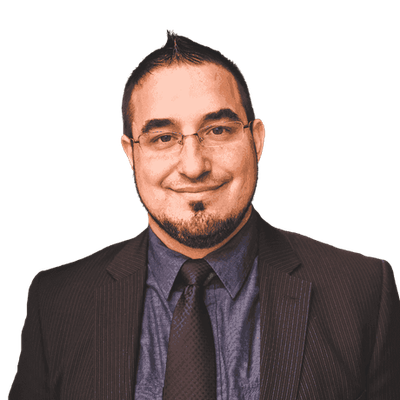
Matthew MontsDeOca is an independent mortgage broker based in Austin — Texas’s state capital — licensed to help buyers and homeowners across the entire state, from Houston and San Antonio to Dallas-Fort Worth and everywhere between. Because Wise Capital shops a panel of lenders instead of selling one bank’s products, you get advice on which program actually fits, including when this one is not the right answer.
Your questions, answered
Do I have to live on a farm to use a USDA loan?
Do USDA loans have a down payment?
Are there income limits for USDA loans?
What credit score do I need for a USDA loan?
Is there mortgage insurance on a USDA loan?
Can I use USDA for a rental or second home?
Can I refinance a USDA loan?
How do I find out if a home is USDA-eligible?
Book a free 30-minute call
Not ready to apply? Talk it through first. We will look at your numbers and tell you honestly what your best move is.
- 30 minutes, by video (Google Meet) or phone
- Free, with no obligation to apply
- A clear next step, whether that is applying now or fixing one thing first
- You talk to a licensed loan officer, not a call center
Pick a time that works for you
Choose a slot on the calendar and you will get a confirmation by email. No obligation, no pressure.
Prefer to talk now? Call 512-588-2771 · open the calendar in a new tab.
Let us show you what you qualify for.
Check your options in a few minutes, or book a quick call and we will walk you through it.
Or call 512-588-2771 · Free, no obligation
Keep learning, in plain English
Other loan programs
USDA loans are guaranteed by the U.S. Department of Agriculture Rural Development program. Wise Capital Mortgage is not affiliated with, endorsed by, or acting on behalf of the USDA or any government agency.
*0% down payment applies to properties in USDA-eligible areas and borrowers whose household income is within program limits; the home must be your primary residence. USDA loans require an upfront guarantee fee and an annual fee. Credit, income, property and underwriting requirements apply. Interest rates and APR depend on your credit profile, loan amount and market conditions. Ask us for a personalized Loan Estimate.
Wise Capital Mortgage, LLC · 5900 Balcones Drive #23333, Austin, TX 78731 · NMLS #2092335 · Equal Housing Lender. Matthew MontsDeOca, NMLS #1034513. This page is for general information and is not a commitment to lend or an offer of credit. Loan programs, eligibility, terms and rates are subject to change and to underwriting approval. You can verify our licensing at the NMLS Consumer Access website, nmlsconsumeraccess.org.