Refinance in Texas: get the money back trapped in your mortgage
A lower rate. Mortgage insurance you should have dropped years ago. Equity sitting idle while you carry high-interest debt. We run the math in writing and tell you when the answer is “don’t.”
Free, no obligation · or call 512-588-2771
Is your mortgage working as hard as you are?
Most homeowners never re-check their loan after closing. These are the four questions we hear most.
We will tell you when the answer is “don’t.” A refinance that does not pay for itself is not a good deal.
From first call to closing, in four steps
Tell us your situation
A 30-minute call or a short online application: income, savings, credit, and the kind of property you want.
Get a real plan
We compare your options across programs and lenders, explain the costs in plain English, and tell you if anything is worth fixing first.
Get approved
With your documents in hand, we move your file to underwriting and issue the approval you need to move forward with confidence.
Close with confidence
We manage the file through appraisal, underwriting and closing, and keep you updated at every stage.
Five reasons, and rate is only one of them
Lower your rate
When market rates are meaningfully below your note rate, a rate-and-term refinance can cut your monthly payment.
Shorten your term
Move from a 30-year to a 15-year loan if your budget allows, and save interest over the life of the loan.
Switch from adjustable to fixed
Lock in a fixed rate before an adjustable loan resets.
Drop FHA mortgage insurance
Refinance into a conventional loan and say goodbye to insurance that could otherwise last the life of the loan.
Use your equity
Cash-out refinance, HELOC or home equity loan, chosen so you do not give up a good rate to get cash.
Investors: recycle capital
Refinance a renovated or appreciated rental into DSCR financing qualified on rental income.
See if refinancing actually pays off.
We run your breakeven in writing before you commit to anything.
Cash-out refinance, HELOC, or home equity loan?
All three turn equity into cash. Picking wrong is expensive, and the deciding factor is usually your current rate, not the amount you need.
Cash-out refinance
Replaces your mortgage with a larger loan, and you take the difference in cash at closing. Usually fixed-rate. It wins when today’s rates are at or below your current rate, or you need a large lump sum.
HELOC
A revolving credit line behind your existing mortgage, typically variable-rate. Your first mortgage stays untouched. Best for phased renovations or when you do not know the final number.
Home equity loan
A separate fixed-rate, fixed-term loan behind your first mortgage. Best for one defined expense when you refuse to disturb a low first-mortgage rate.
Do not trade away a good rate to get cash
If your current mortgage rate sits well below today’s market, a cash-out refinance means giving up that rate on your entire balance, not just on the cash you take. In that case a HELOC or home equity loan almost always wins.
If your rate is at or above the market, the cash-out refinance usually wins. See our full breakdown in cash-out refinance vs. HELOC, and read when to refinance your mortgage for the timing math.
Not sure which one fits?
A quick call and your current rate are usually enough to point you to the right structure.
Texas cash-out rules, plainly
Any cash-out on a Texas homestead is a Section 50(a)(6) loan, named for the provision of the Texas Constitution that governs it. These are constitutional rules, not lender policy, and no lender can waive them.
| Rule | What it means for you |
|---|---|
| 80% total loan-to-value | You cannot borrow against more than 80% of your homestead’s appraised value, counting every lien. |
| 2% cap on certain fees | Specified closing costs are capped at 2% of the loan amount, excluding certain third-party charges such as the appraisal, survey and title insurance. |
| One at a time | Generally one home equity loan at a time, and no more than one in any 12-month period. |
| 12-day cooling-off | You must receive a prescribed notice at least 12 days before closing, and the loan cannot close sooner. |
| Closing location | Restricted to a lender’s office, a title company or an attorney’s office. |
These are summaries, not legal advice. We walk you through how they apply to your loan.
Streamlines and removing mortgage insurance
If you already have an FHA or VA loan, there may be an easier path. The FHA Streamline and the VA IRRRL lower your rate with reduced paperwork. And if you are paying FHA mortgage insurance, refinancing into a conventional loan can remove it once your equity is high enough.
Learn more about each program: FHA loans, VA loans and conventional loans.
Refinance a rental with a DSCR loan
Homeowners are not the only ones sitting on trapped equity. Refinance a renovated or appreciated rental into DSCR financing, qualified on the property’s rent instead of your personal income, and recycle the capital into your next deal.
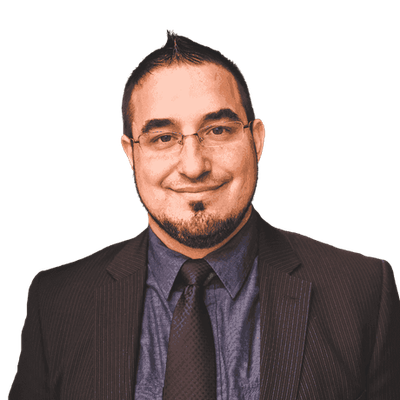
Meet your Refinance loan officer
Matthew MontsDeOca is an independent mortgage broker based in Austin — Texas’s state capital — licensed to help buyers and homeowners across the entire state, from Houston and San Antonio to Dallas-Fort Worth and everywhere between. Because Wise Capital shops a panel of lenders instead of selling one bank’s products, you get advice on which program actually fits, including when this one is not the right answer.
Your questions, answered
How much equity can I take out of my home?
Should I do a cash-out refinance or a HELOC?
Can refinancing remove my FHA mortgage insurance?
How do I know if refinancing is worth the closing costs?
What is the FHA Streamline or VA IRRRL?
Can I refinance an investment property?
What are the Texas rules for cash-out refinancing?
Book a free 30-minute call
Not ready to apply? Talk it through first. We will look at your numbers and tell you honestly what your best move is.
- 30 minutes, by video (Google Meet) or phone
- Free, with no obligation to apply
- A clear next step, whether that is applying now or fixing one thing first
- You talk to a licensed loan officer, not a call center
Pick a time that works for you
Choose a slot on the calendar and you will get a confirmation by email. No obligation, no pressure.
Prefer to talk now? Call 512-588-2771 · open the calendar in a new tab.
Let us show you what you qualify for.
Check your options in a few minutes, or book a quick call and we will walk you through it.
Or call 512-588-2771 · Free, no obligation
Keep learning, in plain English
Other loan programs
A refinance may not lower your total cost, especially if you refinance into a longer term or pay closing costs. Texas homestead cash-out refinances are subject to Section 50(a)(6) of the Texas Constitution. FHA Streamline and VA IRRRL are government-backed programs with their own eligibility rules; Wise Capital Mortgage is not affiliated with HUD, the FHA, the VA or any government agency. Interest rates and APR depend on your credit profile, loan amount and market conditions. Ask us for a personalized Loan Estimate.
Wise Capital Mortgage, LLC · 5900 Balcones Drive #23333, Austin, TX 78731 · NMLS #2092335 · Equal Housing Lender. Matthew MontsDeOca, NMLS #1034513. This page is for general information and is not a commitment to lend or an offer of credit. Loan programs, eligibility, terms and rates are subject to change and to underwriting approval. You can verify our licensing at the NMLS Consumer Access website, nmlsconsumeraccess.org.