Northwest Hills Mortgage Broker: Staying Under the Conforming Limit
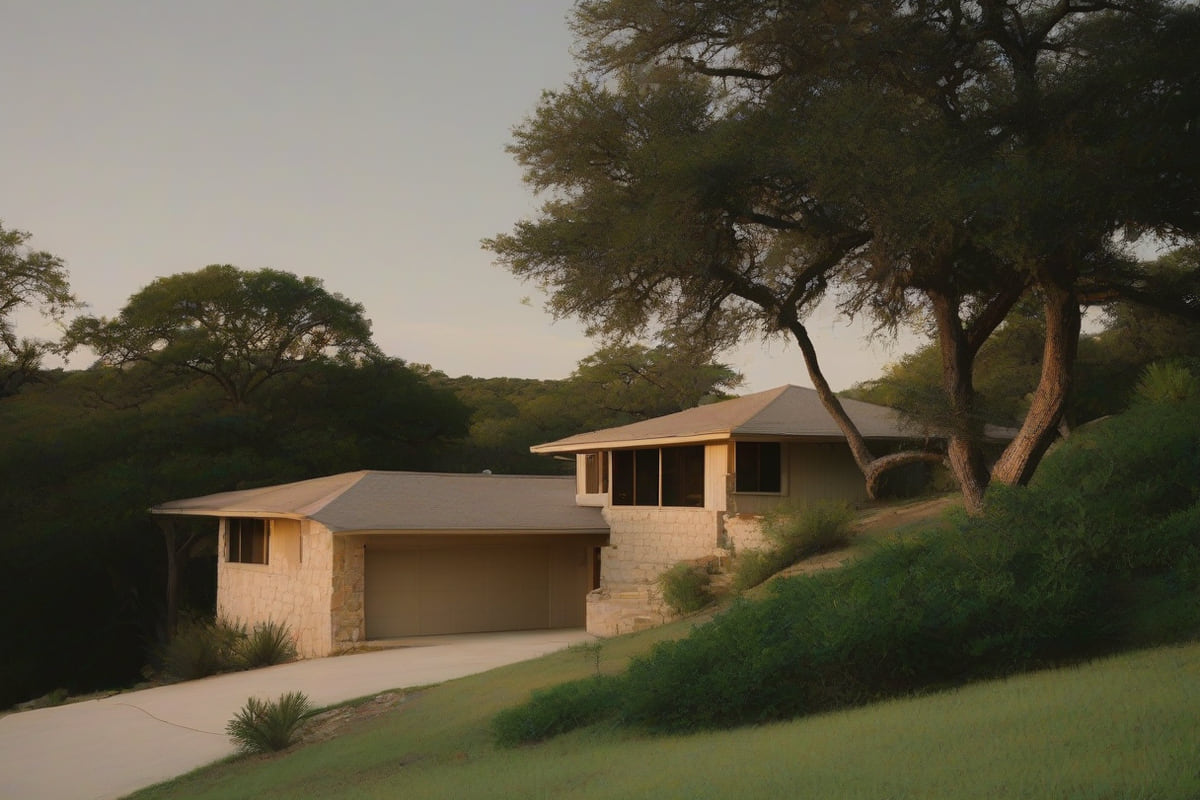
Northwest Hills homes generally trade between $600,000 and $1 million, and that range straddles the most important line in residential lending: the $832,750 conforming limit.
A loan at or below it is priced and underwritten under Fannie Mae and Freddie Mac rules. A dollar above it becomes a jumbo loan, with its own guidelines, reserve requirements and pricing. In this neighborhood, how you structure the down payment often decides which side of the line you land on.
It is also our home neighborhood. Wise Capital Mortgage is on Balcones Drive in 78731, and these are the streets we drive every day.
Buying or refinancing in Northwest Hills? We shop your file across a panel of wholesale lenders.
Three ways to structure a purchase near the line
Take a Northwest Hills purchase where a standard down payment leaves the loan somewhat above $832,750. There are three ways to finance it.
Put enough down to stay conforming
The simplest route. Increase the down payment until the loan amount falls to the conforming limit. You get conforming guidelines and pricing, and you avoid jumbo reserve requirements.
The cost is liquidity. Every dollar that goes into the down payment is a dollar not in reserves, and a buyer who empties savings to stay conforming can end up with a riskier position than a jumbo borrower with cash left over.
Split the financing with a second lien
A piggyback structure uses a conforming first mortgage at or below the limit, plus a second mortgage or home equity line for part of the remaining balance.
It can also avoid mortgage insurance. When the first mortgage is kept at 80% of the price, the first loan carries no mortgage insurance even with a smaller down payment.
The second lien carries a higher rate, and often an adjustable one if it is a line of credit. The comparison has to be made on the blended cost, not the first mortgage rate alone.
It keeps a clean path out. A second lien can be paid down or off without refinancing the first, which is useful if you expect a bonus, an equity vesting or a sale of another property.
Take the jumbo loan
Jumbo pricing is not always worse. Depending on the market and your profile, a jumbo loan at a strong credit score and down payment can price competitively with, or better than, a conforming loan with mortgage insurance.
The trade-offs are stricter: higher reserve requirements, often a lower maximum debt-to-income ratio, and sometimes two appraisals on larger loans.
The right answer depends on your numbers on the day you lock, which is why we price all three side by side rather than assuming.
Split-levels, steep lots and the appraisal
Much of Northwest Hills was built in the 1960s and 1970s on the slopes of the Balcones Escarpment, and the defining house type is the split-level, stepped into the hillside.
Retaining walls deserve their own inspection. On steep lots, a failing wall can be the most expensive repair on the property, and it may not appear in a general inspection report.
Drainage runs toward the house on many uphill lots. Look for regrading, French drains and foundation movement on the uphill side.
Appraisers value split-levels against split-levels. Comparable sales matter, and a heavily renovated house on a street of original split-levels can appraise below its contract price. If you are paying for a renovation someone else did, expect the appraiser to look hard for support.
Taxes in Northwest Hills
Northwest Hills is inside the City of Austin. A typical address carries the City of Austin, Travis County, Austin ISD, Austin Community College and Central Health rates — generally around 1.8% to 2.1% of assessed value combined.
Taxes count toward your debt-to-income ratio, and in this price range they are large enough to affect whether a file qualifies conforming or needs jumbo. Budget on the post-sale assessed value.
File your homestead exemption the year you buy, and verify the parcel with the Travis Central Appraisal District.
Where people buy
The western streets toward Loop 360 carry the highest elevations, the longest views and the steepest driveways.
Around Far West Boulevard, the neighborhood's commercial center, the terrain eases and the inventory includes townhomes and condominiums alongside houses.
The northern edge toward Spicewood Springs Road and Bull Creek runs into wooded creek valleys and larger lots.
The eastern blocks near MoPac offer the quickest route downtown and the flattest lots in the neighborhood.
Allandale, across MoPac, has flat lots and single-story homes at similar prices; Tarrytown to the south moves firmly into jumbo territory.
The neighborhood
Northwest Hills rises west of MoPac into the limestone hills of the Balcones Escarpment, the geological fault line where the Hill Country meets the coastal plain. Most of the neighborhood was developed in the 1960s and 1970s, and its streets follow the contours rather than a grid.
Far West Boulevard is the neighborhood's main street for shopping and dining. Bull Creek District Park to the north has shaded creek pools and trails, and Mount Bonnell, one of the highest points in the city, sits a short drive south above Lake Austin.
Not sure which fits? Compare every loan program we place, or read our jumbo loan guide.
Frequently asked questions
What is the conforming loan limit in Austin? $832,750 for a single-family home. Travis County uses the standard national limit, so any loan above that amount is a jumbo loan.
What is a piggyback loan? A structure that pairs a conforming first mortgage with a second mortgage or home equity line. It can keep the first loan conforming and avoid mortgage insurance, but the second lien carries its own, usually higher, rate.
Is a jumbo loan always more expensive? No. Depending on the market and your credit and down payment, jumbo pricing can be competitive with a conforming loan that requires mortgage insurance. Compare all three structures on the same day.
Should I put more down to avoid a jumbo loan? Sometimes. It gives you conforming guidelines, but it also reduces your cash reserves. The right answer weighs pricing against how much liquidity you keep.
What should I inspect on a steep Northwest Hills lot? Retaining walls, drainage on the uphill side of the house, and the foundation. A structural engineer is worth adding to the general inspection on steep lots.
What are property taxes in Northwest Hills? A typical City of Austin address in Austin ISD carries a combined rate around 1.8% to 2.1% of assessed value.
Price all three before you pick one
Near the conforming line, the structure you choose can matter as much as the rate. Send us the price and your down payment range, and we will lay out conforming, piggyback and jumbo side by side.
Start your application · Run the numbers · Call 737-347-1314
Looking at a property in Northwest Hills?
Send us the address and we will model the real payment — taxes, insurance and HOA included — before you write an offer.
Nearby Areas
Nearby & Related