Frisco Mortgage Broker: New Construction Home Loans
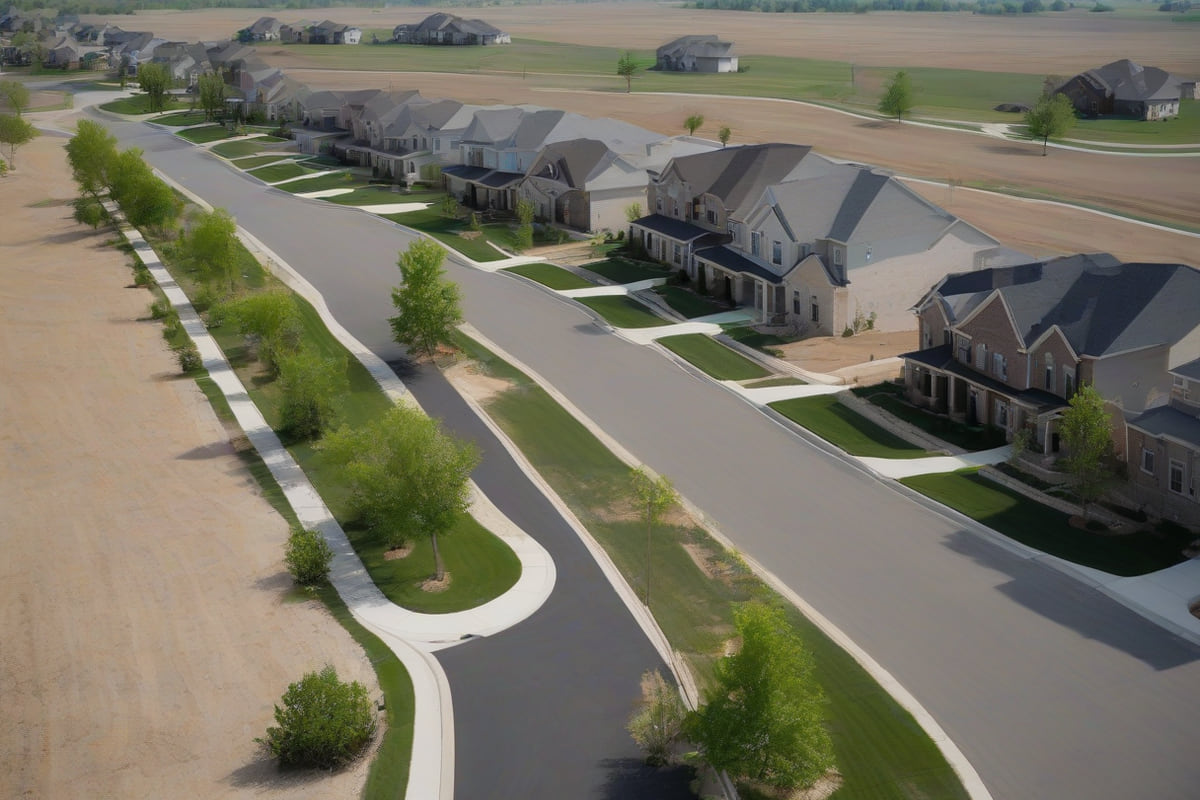
Frisco went from roughly 6,000 people in 1990 to well over 200,000, and almost every house in it was built inside that window. Buying here usually means buying new — sometimes from a plan, on a lot that is currently dirt.
New construction is a genuinely different transaction from a resale, and the differences are not obvious until they cost you something. Here is what actually matters.
The builder's preferred lender, honestly
Builders offer incentives — closing cost credits, rate buydowns, design center allowances — and most of them are conditioned on using the builder's affiliated lender. Buyers reasonably read that as a discount and stop shopping.
Two things are true at once, and both should inform your decision:
The incentive is frequently real and frequently substantial. A large closing cost credit or a meaningful rate buydown can be worth more than anything you would win by shopping. Walking away from it on principle is not sophisticated, it is just expensive.
The incentive is also priced in. It is funded from the builder's margin, and the affiliated lender's rate and fees are not automatically competitive once the credit is accounted for. Sometimes the credit more than covers the difference. Sometimes it does not.
The only way to know is to put the two offers side by side on the same date, comparing total cost over the period you actually expect to hold the loan — not rate against rate, and not credit against credit.
Two practical notes:
- RESPA prohibits a builder from requiring you to use an affiliated lender for the sale itself. What is permitted is conditioning an incentive on it. You may always finance elsewhere; you may simply lose the credit.
- Get a Loan Estimate from both. It is a standardized form for exactly this reason. We will read the builder's side by side with ours and tell you honestly which one wins on your numbers, including when theirs does.
Rate locks when closing is nine months away
This is the hardest problem in new construction financing, and the one most buyers do not see coming.
On a resale you close in about 30 days and lock for 30 days. On a build you may sign a contract 6 to 12 months before the home is finished, and a standard lock does not reach that far.
The options:
An extended lock. Available on many programs at a cost, usually paid up front, covering 180, 270 or sometimes 360 days. You are paying for certainty.
A float-down feature. Some extended locks let you capture a lower rate if the market improves before closing, generally once and within limits. It costs more than a plain extended lock.
Floating and locking later. No cost now, and full exposure to the market between now and closing.
There is no universally correct answer — it depends on how much of your qualifying ratio is already consumed and how much rate movement would actually break your approval. A buyer with room can float. A buyer approved at the edge of their ratio is buying insurance, and should treat the lock cost as insurance rather than a fee.
Delays are normal. Build schedules slip on weather, inspections and supply. Ask what an extension costs before you buy the lock, not when the builder pushes closing by six weeks.
PIDs and MUDs, and what they add to your payment
Much of the newer development in and around Frisco was financed through a Public Improvement District or Municipal Utility District, which issued bonds to build the streets, water, sewer and drainage before the houses existed.
You repay those bonds through an assessment that is additional to your city, county and school taxes.
What that means concretely:
- It is escrowed with your taxes, so it raises your monthly payment
- Because it raises the payment, it reduces how much house you qualify for
- A PID assessment is often a fixed annual amount with a defined payoff term, rather than a rate applied to value
- Two homes at the same price, a mile apart, can differ by a meaningful amount per month because one is in a district and one is not
Ask the builder for the district disclosure and the current assessment before you sign. Texas requires notice, but "provided at signing" and "understood before you committed" are not the same thing. Send it to us and we will build it into the payment rather than letting it appear at closing.
Buying a lot and building custom
Production builds and custom builds finance differently.
On a production build, the builder owns the land and carries the construction cost. You get an ordinary purchase mortgage that closes when the home is complete. Your financing job is the lock and the incentive comparison above.
On a custom build where you own or are buying the lot, you need construction financing. The structure worth asking for is a one-time close — a single loan that funds construction in draws and converts to permanent financing when the home is finished.
Why one-time close is usually better than the two-loan alternative:
- One set of closing costs instead of two
- One credit approval, so a change in your employment or credit mid-build cannot strand you without a permanent loan
- The rate for the permanent phase is generally set up front, sometimes with a float-down at conversion
The tradeoffs are real: fewer lenders offer it, the documentation burden is heavier, and the builder must be approved by the lender — licensing, insurance, financial capacity and a willingness to work within a draw schedule. Line the builder up early, because a builder who will not work inside a lender's draw process cannot be your builder.
Collin County taxes
Combined rates in Frisco generally run in the 1.8% to 2.3% range before any district assessment — City of Frisco, Collin County, Collin College and your school district. Add a PID or MUD on top where one applies.
The city also crosses into Denton County on its western side, which changes the county and college lines.
School districts inside Frisco city limits include Frisco ISD, Prosper ISD, Lewisville ISD and Little Elm ISD. Verify by address with the district — in a city this new, the boundaries were drawn against growth projections rather than neighborhoods.
Verify the parcel with the Collin Central Appraisal District or Denton Central Appraisal District as applicable. On new construction the first year's assessment is frequently based on land only, because the home did not exist on the valuation date. The second year's bill, with the improvement included, is dramatically higher — and escrow shortage notices after year one surprise a great many Frisco buyers. We will project the stabilized payment, not the first-year one.
Where people buy
West Frisco along the Dallas North Tollway and FM 423 carries the newest large-scale development.
Starwood, Stonebriar and Newman Village hold the established higher end, near Stonebriar Centre.
Frisco Square and the Rail District near the original townsite are the densest and most walkable parts of the city, with townhomes and attached product.
Panther Creek and Phillips Creek Ranch are large master-planned communities on the western side.
North Frisco toward Prosper is the current growth front, and the most likely to be inside a newer district.
The city
Frisco began in 1902 as a stop on the St. Louis–San Francisco Railway — the "Frisco" line, which is where the name came from.
It now holds an unusual concentration of professional sport for a city its size: The Star, the Dallas Cowboys' world headquarters and practice facility; Toyota Stadium, home of FC Dallas and the National Soccer Hall of Fame; Comerica Center, the Dallas Stars' practice facility; and Riders Field for the Frisco RoughRiders.
The PGA of America relocated its headquarters here, with two championship courses at PGA Frisco.
The Frisco Heritage Museum and the restored buildings at Frisco Commons preserve what the town was before the growth, and the Frisco Public Art program has placed a large collection of installations across the city.
Not sure which fits? Compare every loan program we place.
Frequently asked questions
Do I have to use the builder's preferred lender in Frisco? No. RESPA prohibits requiring it for the sale. Builders may condition an incentive on using their affiliated lender, so declining can cost you the credit. Compare both Loan Estimates on the same day before deciding — sometimes the incentive genuinely wins.
How do I lock a rate when my home closes in nine months? With an extended lock, available in 180, 270 and sometimes 360 day terms for a fee paid up front, occasionally with a float-down if rates improve. Ask what an extension costs before you buy the lock, because build schedules slip.
What is a PID assessment in Frisco? A Public Improvement District assessment repays bonds issued to build local infrastructure. It is charged on top of your regular property taxes, escrowed with them, raises your monthly payment and reduces how much you qualify for.
Why is my second-year tax bill so much higher? Because the first year was often assessed on land only — the house did not exist on the valuation date. Once the improvement is on the roll, the bill jumps and escrow comes up short. Plan against the stabilized figure, not year one.
What is a one-time close construction loan? A single loan that funds construction in draws and converts to permanent financing at completion — one set of closing costs, one credit approval, and no risk of being unable to qualify for the permanent loan after the build.
What are property taxes in Frisco, TX? Generally about 1.8% to 2.3% combined before any district assessment, varying by school district and by whether the parcel is in Collin or Denton County. Verify with the appropriate appraisal district.
Which school district is my Frisco address in? Frisco ISD, Prosper ISD, Lewisville ISD or Little Elm ISD, depending on the parcel. Verify by address with the district rather than assuming from the city.
Bring us the builder's offer
The most useful thing we do on a Frisco purchase is read the builder's Loan Estimate next to ours and tell you which one actually costs less over the years you plan to keep it.
Sometimes that answer is theirs. You should still know it rather than guess it.
Start your application · Run the numbers · Call 737-347-1314
Looking at a property in Frisco?
Send us the address and we will model the real payment — taxes, insurance and HOA included — before you write an offer.
Talk To A Loan OfficerNearby Areas
Nearby & Related